Start with one SPV. Build the operation that can carry a fund.
You are pooling other people's money into a deal. Work out which vehicle fits, where to form it, who does the back-office work, what it costs, and what happens when the deal ends or a provider changes.
Independent guidance. No provider pays to rank.
Providers covered
Platforms and administrators we examine
Compare what they cover, where they operate, and which responsibilities still sit with you.
Independent coverage. No provider pays to appear, rank, or receive favorable treatment.
The fund-development ladder
Where are you on the ladder?
The legal details change by market, but the operating progression is familiar: one deal, repeated deals, recurring commitments, then a committed portfolio.
Pool investors around one known investment, with one vehicle to form, close, operate, and eventually wind down.
Explore this stage →02Repeat deals, a syndicateBuild a repeatable relationship with backers while keeping each investment and its vehicle distinct.
Explore this stage →03Recurring commitmentsMove toward a rolling or micro-fund model when the strategy and operating cadence are becoming repeatable.
Explore this stage →04Committed capital, a fundRaise against a portfolio mandate and build the operation for calls, investments, reporting, and a multi-year lifecycle.
Explore this stage →Start with the decision in front of you
Fund building is learned in public
The practical lessons are distributed across manager interviews, operating essays, and first-hand accounts. We bring the useful parts together and keep every excerpt connected to its source.
Before committing to Fund I, interview experienced emerging managers to expose the workload, trade-offs, and operating decisions hidden behind the pitch.
 Elizabeth YinCo-founder and General Partner · Hustle Fund
LPs commit for roughly a decade without approving individual investments, so expect their diligence to go deeper than a startup financing.
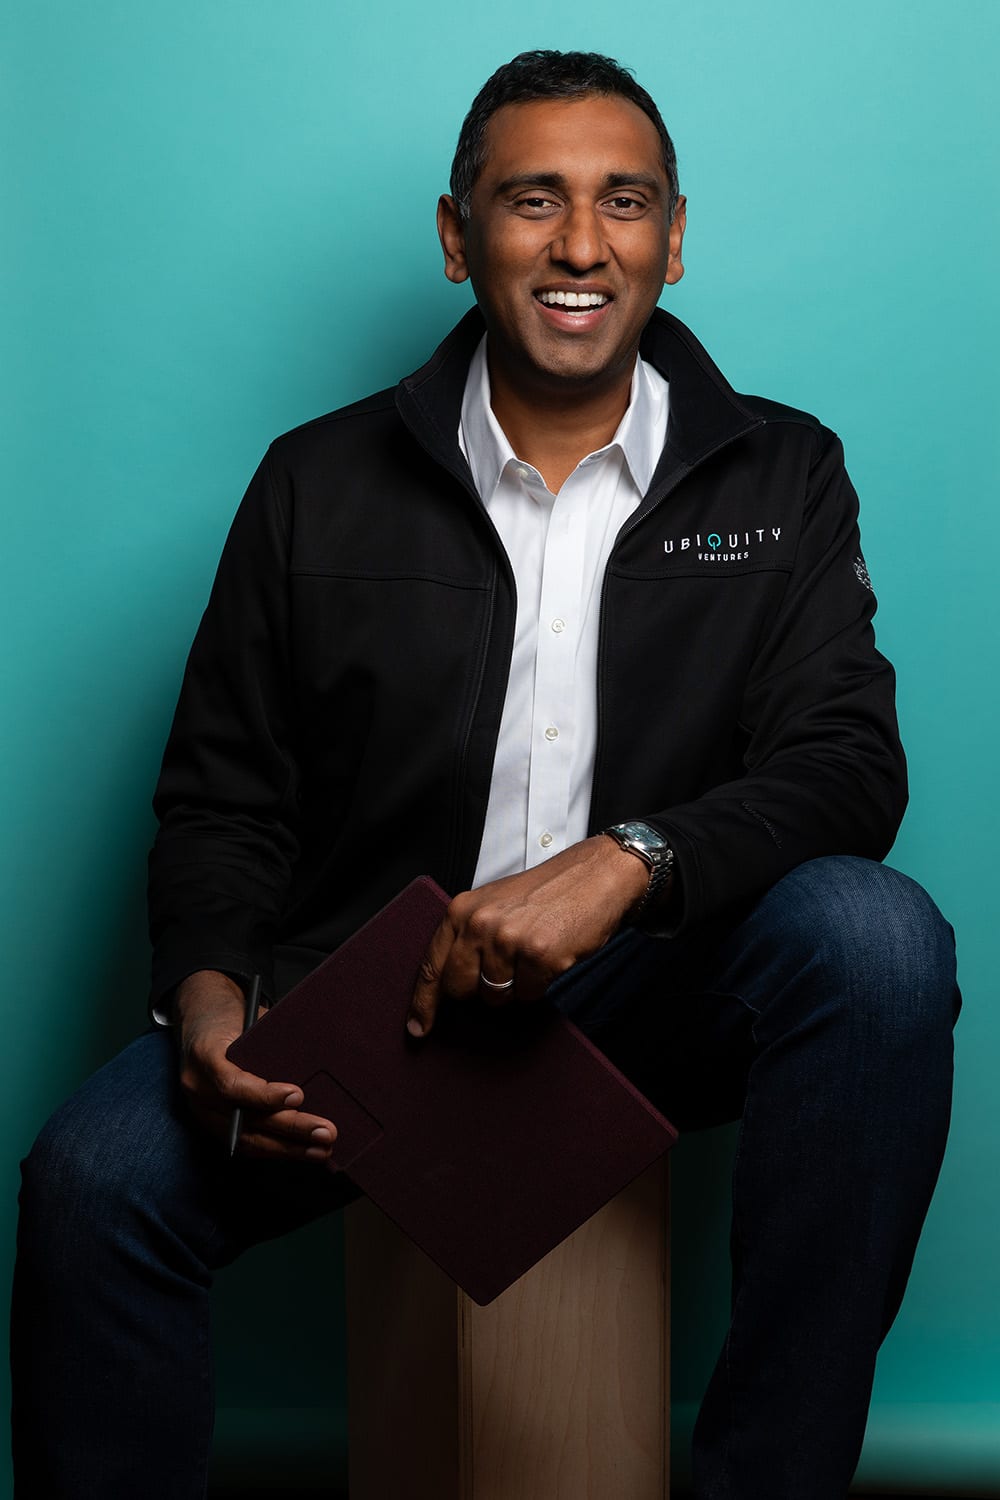 Sunil NagarajFounder and Managing Partner · Ubiquity Ventures
Small angel checks can build investment judgment and a track record before you ask LPs to back a formal fund.
 Sahil LavingiaRolling Fund Lead · shl.vc
For a first fund, individuals, family offices, and strategic corporations may close sooner than large institutions that need a longer relationship.
Elizabeth YinCo-founder and General Partner · Hustle FundEarly commitments create fundraising momentum, but the manager still needs a continuously replenished pipeline of qualified LP prospects.
Elizabeth YinCo-founder and General Partner · Hustle FundLP recommitment is a crucial signal, so operate Fund I as the beginning of a long relationship rather than a single transaction.
 Lisha BellFund Manager · PayPal Economic Opportunity Fund
The market
Providers behind SPVs, syndicates, and funds
See who fits what, where they operate, and which responsibility or price question to verify before you sign.
See all providers| Provider | Best fit | Regions | Structures | What to verify |
|---|---|---|---|---|
 AngelList | You already operate in the US venture ecosystem and want SPVs, syndicates, or a fund in one network | United States; network is global | SPVs, syndicates, rolling and venture funds | Advisory model, network economics, add-ons |
 Carta | You want fund administration and SPV support inside a broader ownership and reporting stack | United States, Europe, APAC | Funds, SPVs, co-investment vehicles | Jurisdiction coverage, service scope, migration |
 Odin | You are an emerging manager launching an SPV or private fund from the UK or Europe | United Kingdom, Europe, international | SPVs and private funds | Entity model, custody partners, ongoing scope |
 Sydecar | You run US deal-by-deal SPVs and want a provider focused on formation and administration | United States | SPVs, syndicates, secondary and layered SPVs | One-time price inputs, complexity, tax scope |
 Allocations | You are a solo GP who wants to run both deal vehicles and funds through one provider | United States; global positioning | SPVs, funds, private assets and migration | All-in price, add-ons, asset eligibility, migration scope |
| VVenture360 | You want a US venture-fund operating system with software and administration in the same relationship | United States | SPVs, venture funds and investor operations | Formation scope, administrator responsibilities, tax and liquidity services |
Practical guides
The questions that come up
Our standard
Useful before it is persuasive.
Every guide and provider profile separates what a primary source establishes, what a provider says, what our analysis concludes, and what remains unconfirmed. Commercial relationships never change a ranking or factual conclusion.
How we work